

Online Auto Loan Preapproval Before You Shop
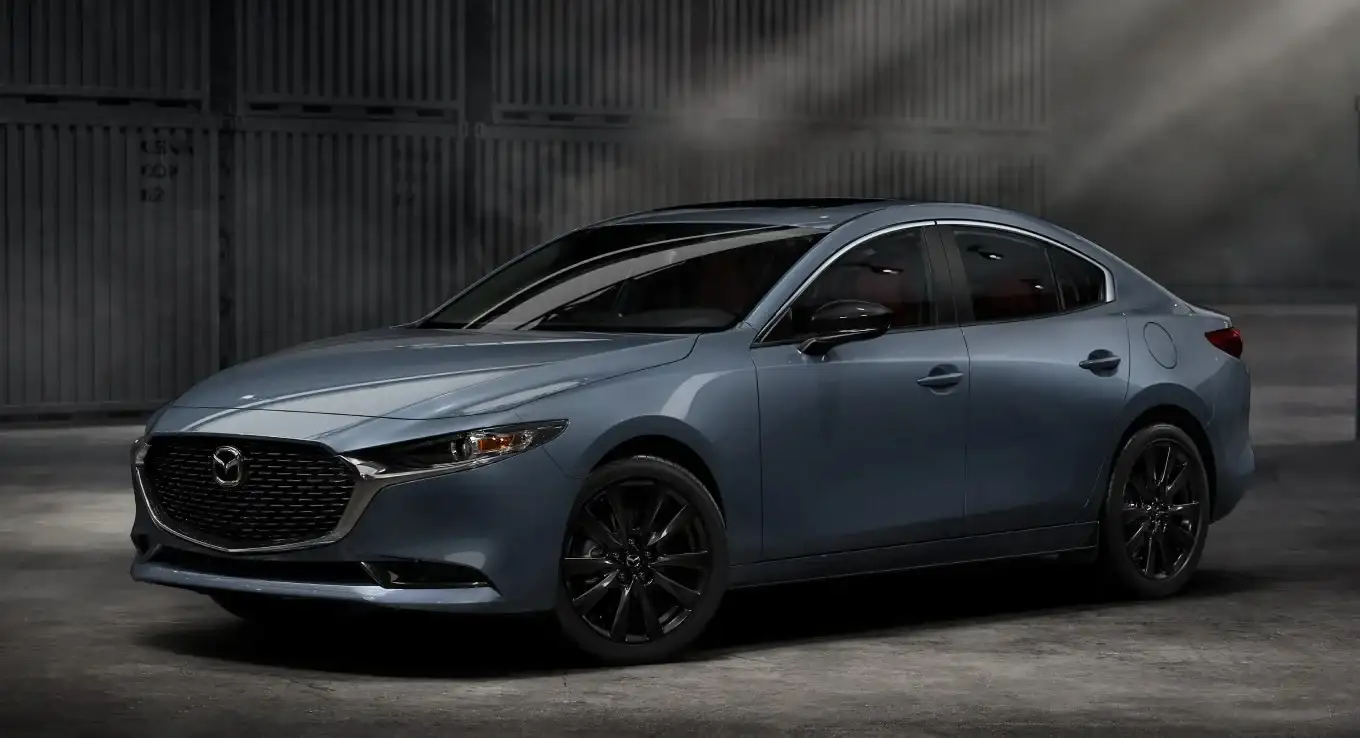
A vehicle search gets clearer the moment you know what financing may look like. Online auto loan preapproval can give Northern New Mexico shoppers a realistic starting point before comparing a Mazda CX-5 with a CX-50, choosing between new and Mazda Certified Pre-Owned, or deciding whether a CX-90 Plug-in Hybrid fits the household.
Preapproval is not a promise that every detail is final. The vehicle, lender requirements, proof of income, and submitted documentation still matter. But it can replace broad guesses with useful information, helping you focus on vehicles that fit your budget and your driving needs.
What online auto loan preapproval means
Online auto loan preapproval is a preliminary lending decision based on information you provide, such as your identity, income, housing details, and credit history. If approved, you may receive an estimated amount you can finance, possible loan terms, and an interest rate or range of rates.
That information helps establish a financing framework before you select a specific vehicle. Once you choose a Mazda, the lender generally reviews the final deal details, including the vehicle identification number, age, mileage when applicable, and final loan amount.
Preapproval differs from prequalification, although the terms are sometimes used casually. Prequalification is often a quick estimate based on limited information and may use a soft credit inquiry. Preapproval typically involves a more complete review and may involve a hard credit inquiry. Every lender handles this differently, so read the application disclosures before submitting.
Why preapproval can make car shopping easier
A preapproval gives you a reference point while you compare vehicles, not a reason to rush into a decision. It can be particularly helpful when the choices have meaningfully different ownership considerations.
For example, a shopper considering a Mazda CX-30 and a Mazda3 may prioritize maneuverability, passenger space, and available all-wheel drive differently than a family comparing the CX-70 and CX-90. A buyer interested in a hybrid or plug-in hybrid may also want to weigh charging access, commute patterns, and long-trip routines alongside the financing structure.
Knowing your potential financing range lets you spend more time on these real-world questions. You can assess whether a new Mazda’s latest safety and technology features are the right fit, or whether a Mazda Certified Pre-Owned vehicle offers the value and coverage you prefer. The goal is not simply to find a payment. It is to choose a vehicle you will feel good driving and keeping.
Preapproval can also make the dealership conversation more efficient. Rather than starting from scratch, you can review your situation with a finance professional, compare available options, and confirm the details tied to the exact vehicle you want.
What lenders usually review
Lenders use several factors to assess an auto loan application. Credit history is one factor, but it is not the only one. They may also consider your income, employment history, monthly housing payment, existing debt obligations, requested loan amount, down payment, and the vehicle being financed.
A strong application is accurate and complete. If your income includes commissions, self-employment earnings, retirement income, or multiple jobs, be prepared for the possibility that a lender may request additional documentation. That is normal underwriting, not necessarily a sign that something is wrong.
The vehicle itself can affect available terms. New vehicles, Mazda Certified Pre-Owned vehicles, and other used vehicles can have different lender guidelines based on age, mileage, title history, and loan-to-value considerations. This is one reason a preapproval should be treated as a helpful starting point rather than the final word.
How to prepare for an online auto loan preapproval
Before applying, take a few minutes to gather accurate information. Doing so can reduce follow-up questions and help prevent delays once you are ready to move forward.
Have your current address and housing payment available, along with employment and income information. You may also need a government-issued ID, Social Security number, proof of income, insurance details, and information about a trade-in if you plan to use one. Requirements vary by lender and individual application.
It also helps to consider your preferred down payment and trade-in separately from the loan request. A larger down payment can reduce the amount financed, but it should not leave you without a practical cash cushion for normal household needs. The right amount depends on your overall financial picture.
If you have a trade-in, understand its condition as honestly as possible. Mileage, maintenance history, tires, cosmetic wear, accident history, and market demand all influence its value. A final appraisal happens in person because a vehicle needs to be inspected, but having the basic details ready gives the process a cleaner starting point.
Online auto loan preapproval and your credit
Many shoppers hesitate to apply because they worry about their credit score. The best approach is to understand the type of credit inquiry involved before you consent.
A soft inquiry generally does not affect your score and is commonly used for preliminary offers. A hard inquiry may affect your score, usually by a limited amount, and is often used when a lender performs a full credit review. The application should explain which inquiry may be used.
If you are comparing financing offers, keep your shopping focused within a relatively short period. Credit-scoring models often recognize that consumers may compare auto financing, though the exact treatment can vary by scoring model and lender. Avoid opening unrelated credit accounts while you are preparing to finance a vehicle, and make every existing payment on time.
If your credit is still developing or has been affected by a recent life event, do not assume financing is out of reach. Approval terms depend on the full application. A straightforward conversation with a finance team can help you understand available paths without pretending that every borrower will receive the same outcome.
Compare the whole loan, not just the monthly payment
A monthly payment matters, but it does not tell the whole story. Loan term, interest rate, amount financed, down payment, trade-in value, taxes and fees, and optional products can all affect the final agreement.
A longer term may lower the monthly payment, yet it can increase the total interest paid over the life of the loan. A shorter term can build equity more quickly, but the higher payment needs to fit comfortably into your monthly budget. There is no universal best term. The right choice balances payment comfort, overall cost, expected ownership period, and the vehicle you choose.
Ask for clear answers about the annual percentage rate, number of payments, total amount financed, and any conditions required for approval. If something is unclear, pause and ask. Buying a car should feel as good as driving one, and clarity is part of that experience.
Questions to ask before selecting a vehicle
Once you have preapproval information, use it to guide a better vehicle comparison. For a family SUV, think beyond seating capacity. Consider how often you carry passengers, whether rear-seat access matters, cargo needs for weekend travel, and whether available driver-assistance features align with your priorities.
For a CX-90 Plug-in Hybrid shopper, the question may be whether home charging supports your daily driving pattern. For an MX-5 Miata buyer, the decision may center on driving enjoyment, storage expectations, and whether it is a primary vehicle or a second car. For a value-focused shopper, comparing a new model with Mazda Certified Pre-Owned options can reveal different benefits around condition, warranty coverage, features, and financing availability.
This is where preapproval supports a thoughtful purchase rather than dictating it. It gives you a range, while the test drive and vehicle comparison tell you whether the choice is right.
When to apply and what happens next
Apply when you are serious enough to begin narrowing your options, but before you feel pressure to make a same-day decision. Preapprovals may have expiration dates, and lender terms can change, so applying far too early can create unnecessary repeat work.
After submitting an online application, review the response carefully. Confirm whether it is a prequalification or preapproval, whether a credit inquiry was used, what documents are still needed, and whether the decision is tied to conditions. Then choose vehicles that suit your needs and bring your information with you when you are ready to finalize the process.
At Santa Fe Mazda, shoppers can compare Mazda vehicles and financing options in one place, with specialists who understand the lineup from the Mazda3 to the CX-90. Start with a clear application, take the vehicle that fits your life for a proper drive, and let the final financing conversation be as transparent as the rest of your decision.
Frequently Asked Questions
Can I apply for auto financing online with Santa Fe Mazda?
Yes. Santa Fe Mazda has an online finance application on its website, so you can submit your information before visiting. The finance team can then review options with you and confirm the details for the specific Mazda you choose. Final approval still depends on verification and the vehicle selected.
How long does an auto loan preapproval last?
It depends on the lender. Many preapprovals include an expiration date, and rates can change before you finalize a purchase. Check the date on your approval letter or online response, and plan to choose a vehicle within that window so you do not have to reapply.
Can I bring a credit union preapproval to a Mazda dealer in Santa Fe?
Generally, yes. Many shoppers in Santa Fe, Los Alamos, and Española arrive with a preapproval from a bank or credit union. The dealership can work with that financing or show you other options, and comparing the APR, term, and total cost of each offer helps you choose.
Can I get preapproved if I am self-employed?
Self-employed buyers can be preapproved, but lenders usually ask for more documentation to verify income. Tax returns, bank statements, and business records are common requests. Having them ready before you apply can prevent delays, and accurate income figures help the lender give you a realistic answer.
0 comment(s) so far on Online Auto Loan Preapproval Before You Shop