

Bad Credit Financing for Your Next Mazda
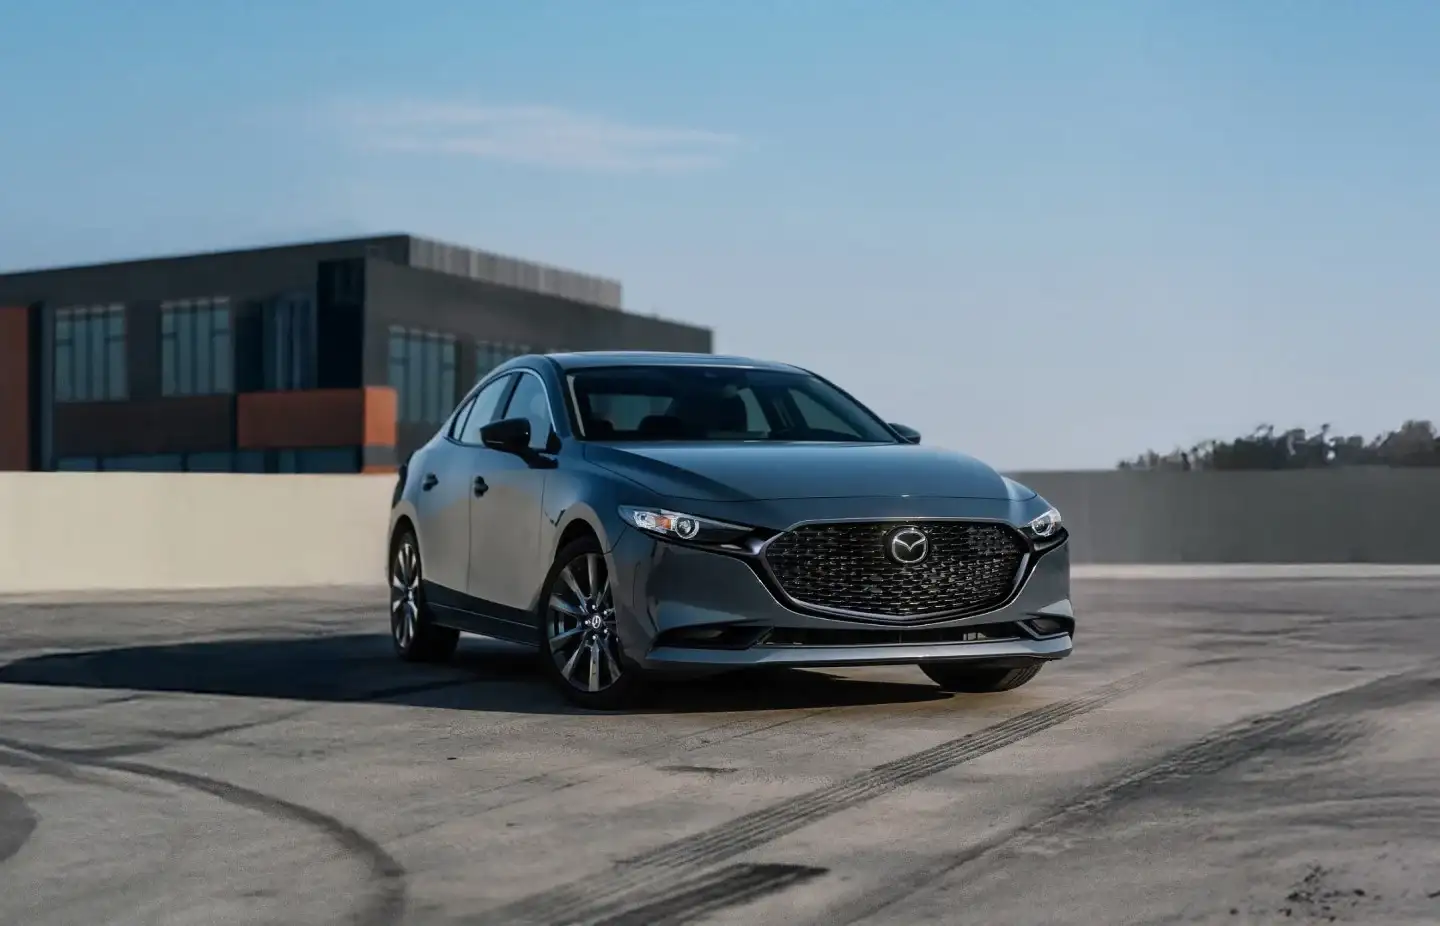
A lower credit score should change how carefully you shop for a vehicle, not whether you can shop at all. Bad credit financing can help qualified buyers move forward, but the best outcome comes from understanding the loan terms, choosing a vehicle that fits the full monthly budget, and avoiding decisions made under pressure.
For Northern New Mexico drivers, that may mean comparing a new Mazda with a Mazda Certified Pre-Owned option, considering how much space a growing family needs, or deciding whether an efficient Mazda3, capable CX-5, or three-row CX-90 is the better long-term fit. The finance plan should support that decision, not override it.
What Is Bad Credit Financing?
Bad credit financing is an auto loan option designed for buyers with low credit scores, limited credit history, past late payments, collections, bankruptcy, or other credit challenges. Lenders look beyond a single score. They may also review income, employment stability, residence history, existing debt, loan amount, down payment, and the vehicle being financed.
Approval is never guaranteed, and terms can vary widely. A borrower with steady income and a meaningful down payment may receive different options than someone with the same credit score but a higher debt load or inconsistent income. That is why an online score alone cannot tell you exactly what loan you will qualify for.
A dealership finance team can submit an application to appropriate lending sources and explain available terms in plain language. At Santa Fe Mazda, the goal is to keep the purchase process efficient and transparent, with vehicle selection, financing, and specialized Mazda support under one roof.
What Lenders Usually Review
Credit history matters, but it is only one piece of an auto financing application. Lenders want to know whether the payment is realistic based on your current situation.
Income is central. Be prepared to document your earnings through recent pay stubs, bank statements, tax documents, or other proof of income when requested. Lenders also consider monthly obligations, including housing, credit cards, personal loans, child support, and other vehicle payments. A buyer who earns enough to cover the proposed payment but carries substantial monthly debt may have fewer choices.
The vehicle itself also affects the application. A newer vehicle or Mazda Certified Pre-Owned model can sometimes offer different financing opportunities than an older, higher-mileage used vehicle. This does not mean new is automatically the right answer. A Certified Pre-Owned Mazda may offer the balance of value, vehicle condition, and coverage that makes sense for a particular buyer.
A down payment can help as well. It lowers the amount financed, may reduce lender risk, and can improve the payment structure. The right amount depends on your savings and your need to keep an emergency cushion. Draining every available dollar for a down payment can create a different financial problem later.
Focus on the Total Loan, Not Just the Payment
A low advertised monthly payment can be misleading when viewed by itself. Extending a loan term can reduce the monthly amount while increasing the total interest paid and keeping you in the loan longer. If the vehicle depreciates faster than the balance declines, you could owe more than the vehicle is worth for a period of time.
Ask to review the complete financing picture: the annual percentage rate, loan term, amount financed, total of payments, and any optional products included in the contract. If something is unclear, ask for an explanation before signing. A trustworthy finance conversation should leave room for questions.
It also helps to build a vehicle budget that includes more than the payment. Account for insurance, fuel or electricity, registration, maintenance, tires, and expected repairs outside of warranty coverage. A CX-30 may fit a commuter’s needs with a manageable ownership footprint, while a CX-50 or CX-5 could make more sense for drivers who regularly carry passengers, cargo, or outdoor gear. The best vehicle is the one that works for both your life and your finances.
Steps to Take Before Applying for Bad Credit Financing
Start by reviewing your credit reports for accuracy. Incorrect late payments, accounts that do not belong to you, and reporting errors can affect your score and should be disputed with the credit bureau. You do not need perfect credit to apply, but you should know what a lender is likely to see.
Next, gather your documents before visiting the dealership. Having identification, proof of residence, proof of income, insurance information, and details about a trade-in can make the process smoother. If you have a trade-in with a remaining balance, bring the payoff information too.
Then decide what monthly ownership cost feels sustainable. Give yourself room for normal life expenses and unexpected ones. A loan that technically receives approval may still not be the right loan for your household.
Finally, consider whether a co-applicant is appropriate. A qualified co-applicant may strengthen an application, but both people become responsible for the debt. This is a serious commitment, not a casual favor, and should be discussed openly before submitting an application.
New, Used, or Mazda Certified Pre-Owned?
Bad credit financing does not require choosing a particular type of vehicle. The right choice depends on your needs, available inventory, expected driving, and loan options.
A new Mazda can be appealing for buyers who want the latest safety and driver-assistance features, full factory warranty coverage, and current powertrain choices. Drivers interested in electrified options may also want to compare hybrid and plug-in hybrid models based on their daily route, home charging access, and fuel-use goals.
A used vehicle can reduce the amount financed, but condition and history matter. Look beyond the odometer. Review maintenance records when available, inspect the vehicle carefully, and consider how age and mileage may affect future repair needs.
Mazda Certified Pre-Owned can be a strong middle ground for value-focused shoppers. These vehicles undergo a detailed inspection process and include certification benefits that can provide added confidence compared with a typical used vehicle. Availability changes, so compare current options based on your preferred size, features, condition, and financing terms.
Avoid These Common Financing Mistakes
The most expensive mistake is shopping only by monthly payment. It can lead to a longer-than-needed loan, a higher overall cost, or a vehicle that stretches the budget too far.
It is also wise to avoid applying everywhere without a plan. Auto loan credit inquiries made during a focused shopping window may be treated differently by scoring models than scattered applications over a long period, but it is still smart to apply thoughtfully. A dealership finance department can help you understand the application process and the information required.
Be cautious of offers that promise approval without discussing income, terms, or the full contract. Responsible financing involves verification and clear disclosures. If a deal feels rushed or vague, pause and ask questions.
Do not overlook the value of timely payments after purchase. Consistent on-time auto payments may help strengthen your credit profile over time. Automatic payments or calendar reminders can reduce the chance of an accidental late payment, provided your account has sufficient funds.
Questions Worth Asking in the Finance Office
Before finalizing an auto loan, ask what the APR is, how long the loan lasts, whether there is a prepayment penalty, and what your total payment obligation will be. Ask which products are optional and which are required by the lender. If you are trading in a vehicle, confirm how its value and any existing payoff are being handled.
You can also ask whether a larger down payment, a different vehicle, or a different term would change the available options. These questions are not a sign that you are difficult to work with. They are how you make an informed decision.
A Better Starting Point for Your Next Vehicle
Bad credit financing works best when it is paired with a realistic budget, complete information, and a vehicle you will be comfortable owning well beyond the first drive home. Whether you are comparing a Mazda3 with a CX-30, looking for a family-ready CX-90, or considering Mazda Certified Pre-Owned inventory, take time to match the vehicle and loan to your actual needs.
When you are ready, bring your questions, documents, and wish list to Santa Fe Mazda. A straightforward financing conversation can help you identify available paths and take the next step with more confidence.
Frequently Asked Questions
Can I get a Mazda with bad credit in Santa Fe?
Many buyers with credit challenges do finance a vehicle, though approval is never guaranteed and terms vary. Santa Fe Mazda offers an online finance application, so you can see what options are available before you visit. Income, existing debt, down payment, and the vehicle you choose all affect the outcome.
Will a past bankruptcy stop me from financing a Mazda?
Not necessarily. Some lenders work with buyers who have a bankruptcy on their record, especially once it has been discharged and newer accounts show on-time payments. Expect to provide documentation and to see higher rates than borrowers with strong credit. Reviewing several offers helps you find terms you can manage.
Can I refinance my Mazda loan later if my credit improves?
Refinancing is often possible once your credit score and payment history improve, and it may lower your rate or payment. Before signing your original loan, ask whether it has a prepayment penalty, since that can affect the savings. Consistent on-time payments are the most reliable way to build toward better terms.
How can I find an affordable used vehicle in Santa Fe while rebuilding credit?
Look for a reliable vehicle that keeps the total cost manageable, not just the payment. The Santa Fe Mazda website lists budget-friendly used vehicles and pre-owned specials alongside certified inventory. Review the vehicle history and condition, and compare insurance and fuel costs before you choose.
0 comment(s) so far on Bad Credit Financing for Your Next Mazda